

Apple’s business is unusually simple for a company worth almost $4.5 trillion: sell premium devices, then monetize an installed base through services, subscriptions and an ecosystem that makes leaving increasingly inconvenient.
Revenue split: iPhone 53%, Services 25% (App Store, iCloud, Music, TC) Wearables & iMac & iPad 22%.
The problem has not been profitability. It has been growth. But In Q3 2026 growth is back at 16% - is that a buy signal?
To answer that question let’s dive into the financials.
What changed beneath the surface
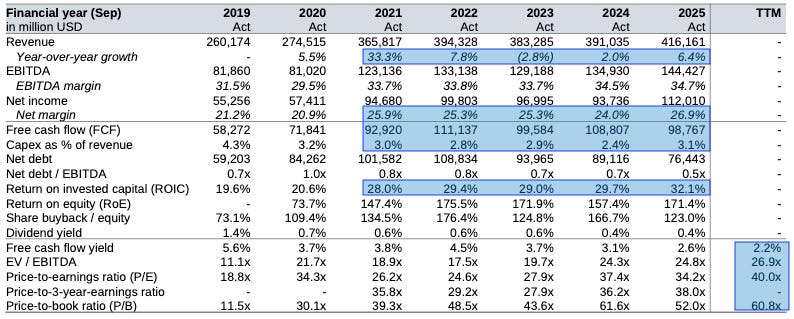
A short glimpse at the block at the bottom right reveals: This is not cheap. Stable compounders are expected to trade at a FCF yield of 3-4% (not 2.2%), a PE ratio of 25-30x (not 40x) and and EV / EBITDA of 15-20x (not 27x). Values closer to Apples historical levels.
→ A short recap on what these metrics mean and how to evaluate them HERE.
Apple’s historical financials explain why investors are willing to pay a premium.
Revenue increased from $260 billion in 2019 to $416 billion in 2025 - an annual growth of 8% - that’s decent but not impressive.
The more impressive numbers sit below revenue.
Net margin increased from 21% to 27% showing that the business is getting more cost efficient while defending market share. Only companies with a strong competitive advantage can achieve that in such a stable manner.
ROIC increased from 19.6% to 32.1%. In plain words: Every dollar invested generates substantially more value, a sign of efficiency. For comparison: a normal ROIC for such as business is only 12%.
Net debt fell from $109 billion in 2022 to $76 billion in 2025 strengthening the balance sheet. Banks look at the Net debt to EBITDA ratio which is at 0.5x - an extremely strong value (below 1.5x is considered strong).
And Apple generated approximately $100 billion of FCF in 2025 with a constant trend.
Apple requires surprisingly little physical investment. Only 3% of the companies sales are reinvested in the business. Amazon, Google or Meta use rates of above 20% during the AI boom.
That means management does not yet see a reason to commit tens of billions of shareholder capital to infrastructure before the economics of AI monetization become clearer.
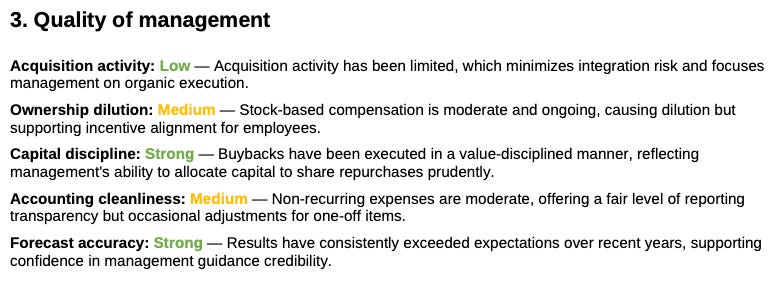
The Financial X-Ray consequently rates management quality Strong, highlighting disciplined capital allocation and reliable forecasting.
But restraint only creates value if Apple is right.
That means for now Apple can generate enormous profits without continuously pouring a large share of its revenue back into factories and infrastructure.
Q3 2026
In Q3 2026, revenue increased 16% to $109.4 billion. iPhone sales reaccelerated sharply by 22%, with the Services segment expanding double digits as well. That’s an increase we haven’t seen in 4 years. Profitability and cash generation are equally strong.
Greater China is particularly relevant because weakness there had been one of the major concerns surrounding Apple.
That changes the investment discussion. A return to double-digit growth makes the premium easier to defend.
The pattern at work
Apple doesn’t fit one of the negative Financial X-Ray patterns we’ve discussed.
The financial picture is remarkably clean:
Revenue: growth reaccelerating in Q3
Net margin: strong at ~27%
FCF: medium due to weak growth
ROIC: strong >30%
Management quality: strong
Valuation: normal
The tension is the gap between business quality and the return investors can reasonably expect from today’s price.
Valuation & why investors may misread it
Look at Apples current valuation of $4.45T today. It generates approximately $100 billion of annual FCF = a yield of 2.2% ( below the historical average of 3-4%).
Investors accept that low current cash return because they expect Apple’s cash generation to grow substantially.
Now assume Apple’s valuation gradually normalizes and the stock trades at a still-premium 3% FCF yield in five years.
For you to make a 10% annual return on the stock for five years, FCF would need to grow at 17%. If the yield stays at 2.2%, FCF would have to grow by 10%.
Now compare that with history.
From 2019 to 2025, FCF compounded at only around 9% annually.
The Financial X-Ray does the thinking for you and visualizes the fair value in a chart.
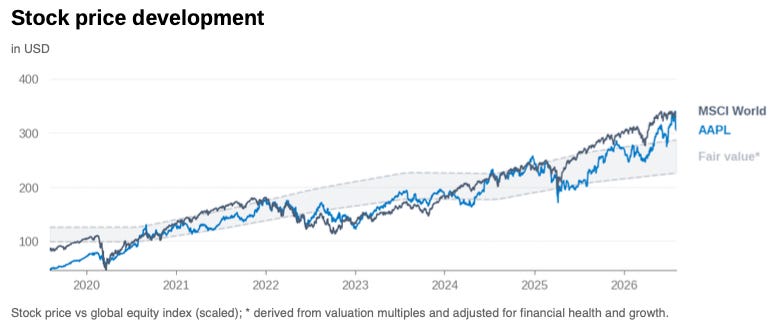
With the stock trading near the upper end of the fair value band investors should expect a lower return from an investment.
The insight
Apple’s financial quality is difficult to fault.
Margins are around 35%. ROIC exceeds 30%. Capex remains unusually low. Debt is declining. The company generates around $100 billion of FCF annually, and Q3 suggests revenue and iPhone growth may be reaccelerating.
Management’s reluctance to join the AI infrastructure spending race may ultimately prove sensible. Apple has the financial strength to invest when the economics justify it rather than simply because competitors are spending.
But investors are already paying heavily for that quality.
At a 2.2% FCF yield, a 10% annual return becomes difficult if Apple’s valuation moves even modestly toward historical norms. At a 3% FCF yield five years from now, roughly 17% annual FCF growth would be required to support that return.
It is achievable, but not a free lunch.
The Financial X-Ray makes the distinction visible: the business has exceptional margins, capital efficiency and management quality. The investment case depends on whether future cash-flow growth can justify the valuation investors already place on those strengths.
Perform that a quick sanity check on financial strength, management quality and valuation across any stock in the X-Ray universe. Stocks with an X-Ray score of strong have outperformed the S&P 500 significantly.
Thank you for sharing this fascinating breakdown of Apple's valuation and growth metrics! Apple's return to 16% revenue growth in Q3 2026 demonstrates clear operational resilience, even with its net debt dropping to $76 billion and ROIC hitting 32.1%. While a 40x P/E ratio leaves little room for error, seeing a tech giant expand net margins to 27% while reinvesting just 3% of sales shows how powerful their ecosystem moat remains. Check out Capital Libre to explore simple breakdowns of these shifting market dynamics!