

Delta is one of the largest U.S. airlines, earning money primarily from passenger tickets (90%), with additional revenue from premium cabins, its loyalty partnership with American Express, cargo and maintenance services and an oil refinery that supplies and helps manage the cost of a significant portion of its jet-fuel needs.
The investment case looks straightforward: free cash flow has recovered, debt is falling and the stock trades at roughly 11.5x earnings.
But airlines have structurally difficult economics. Aircraft require continuous investment, margins are relatively thin, fuel prices are largely outside management’s control and demand is cyclical.
So what changed beneath the surface
Delta’s recovery since the pandemic is real.
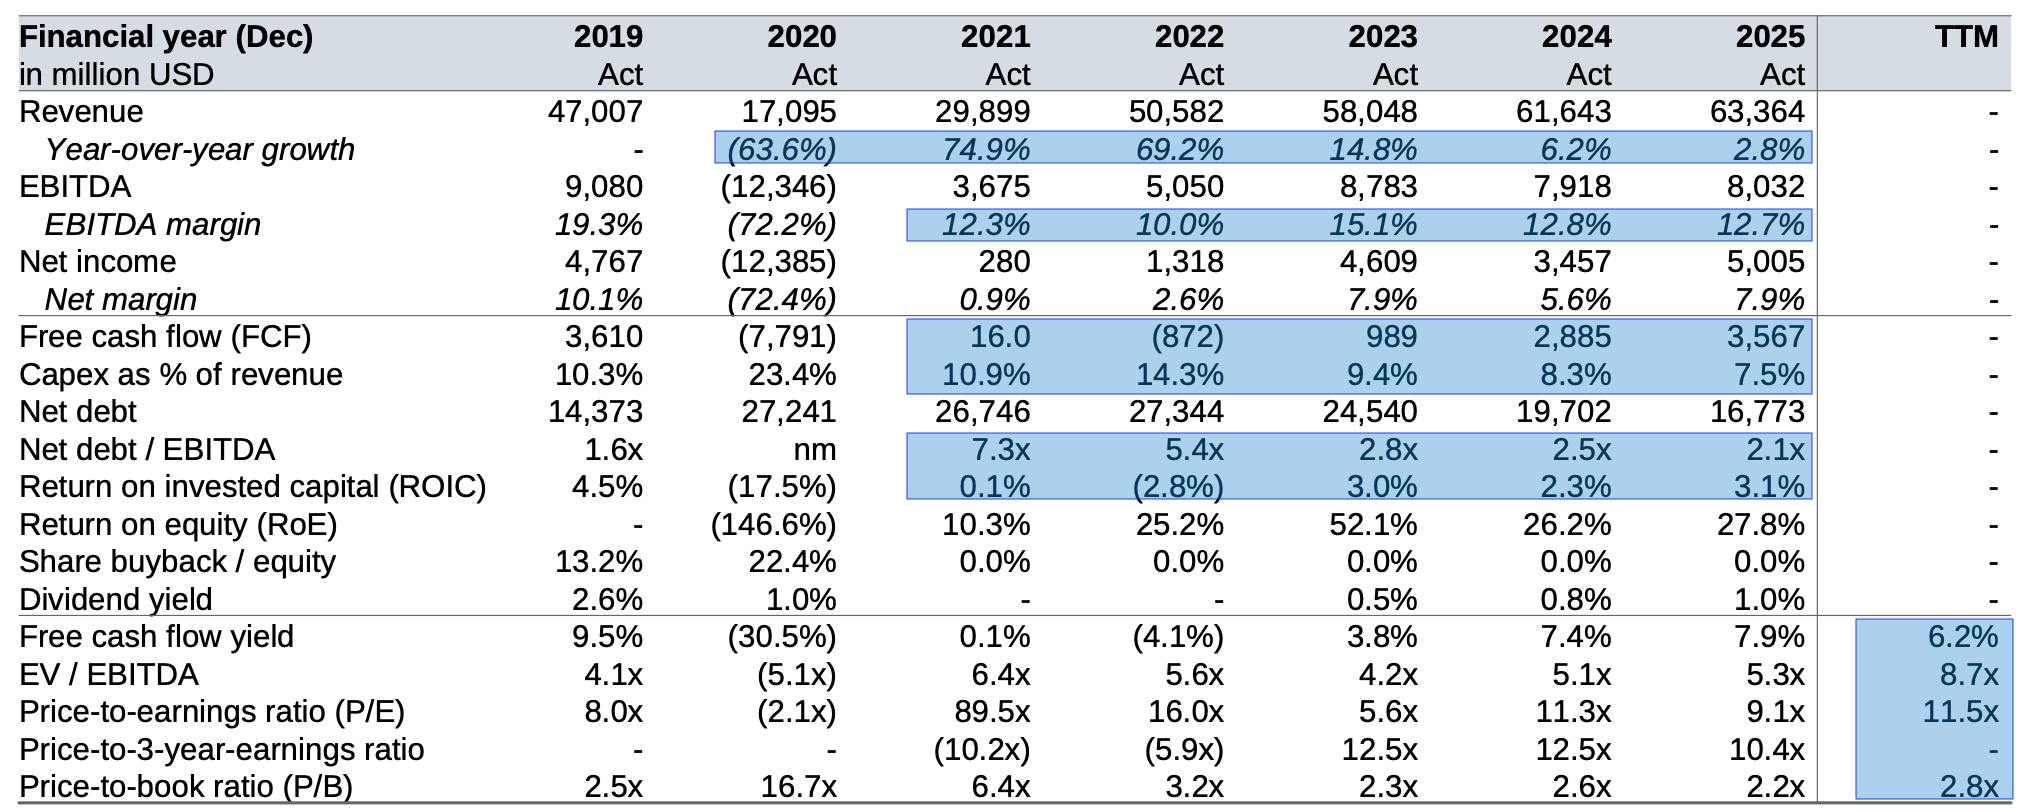
Revenue reached $63.4 billion in 2025, up from $47.0 billion in 2019. FCF recovered to $3.6 billion, while net debt fell from $27.3 billion in 2022 to $16.8 billion.
Those are meaningful improvements. Delta is generating cash again and repairing its balance sheet.
But the quality of those earnings matters.
EBITDA margins have generally remained around 10–15% since 2022, versus 19.3% in 2019, while ROIC was only 3.1% in 2025. ROIC measures the operating profit per dollar invested and a level above the companies cost of capital (approx 8-10%) would be value accretive.
Why does that matter?
Airlines require enormous amounts of capital to generate their revenue. Aircraft need to be purchased, maintained and eventually replaced. A low return on invested capital therefore tells us that large amounts of investment have historically produced relatively modest economic returns.
That is very different from a capital-light business that can grow without continuously reinvesting billions.
Q2 shows the problem: Delta’s latest quarter was not weak from a demand perspective. Adjusted revenue increased 13.9%. Passenger revenue grew 13%, premium revenue 17% and loyalty-related revenue 19%, while capacity increased only around 1%.
That is strong commercial performance. But operating expenses increased 20%. Fuel expense increased 77%, while even non-fuel unit costs rose 6.8%.
The result:
Revenue: +13.9%
Operating income: -24%
Operating margin: 13.3% → 8.8%
Free cash flow: $733m → $209m
This is the central issue.
Delta sold substantially more, but kept substantially less.
Fuel prices were the largest driver, and Delta cannot control them. Higher ticket prices can compensate, but only to a point because passengers can switch airlines or reduce travel altogether. As a buffer against oil-price shocks and as a competitive advantage, Delta owns the Monroe refinery that generated an operating profit 350 million in Q2, however not enough to offset the risen input costs.
That makes future profitability inherently harder to predict.
The pattern that becomes visible
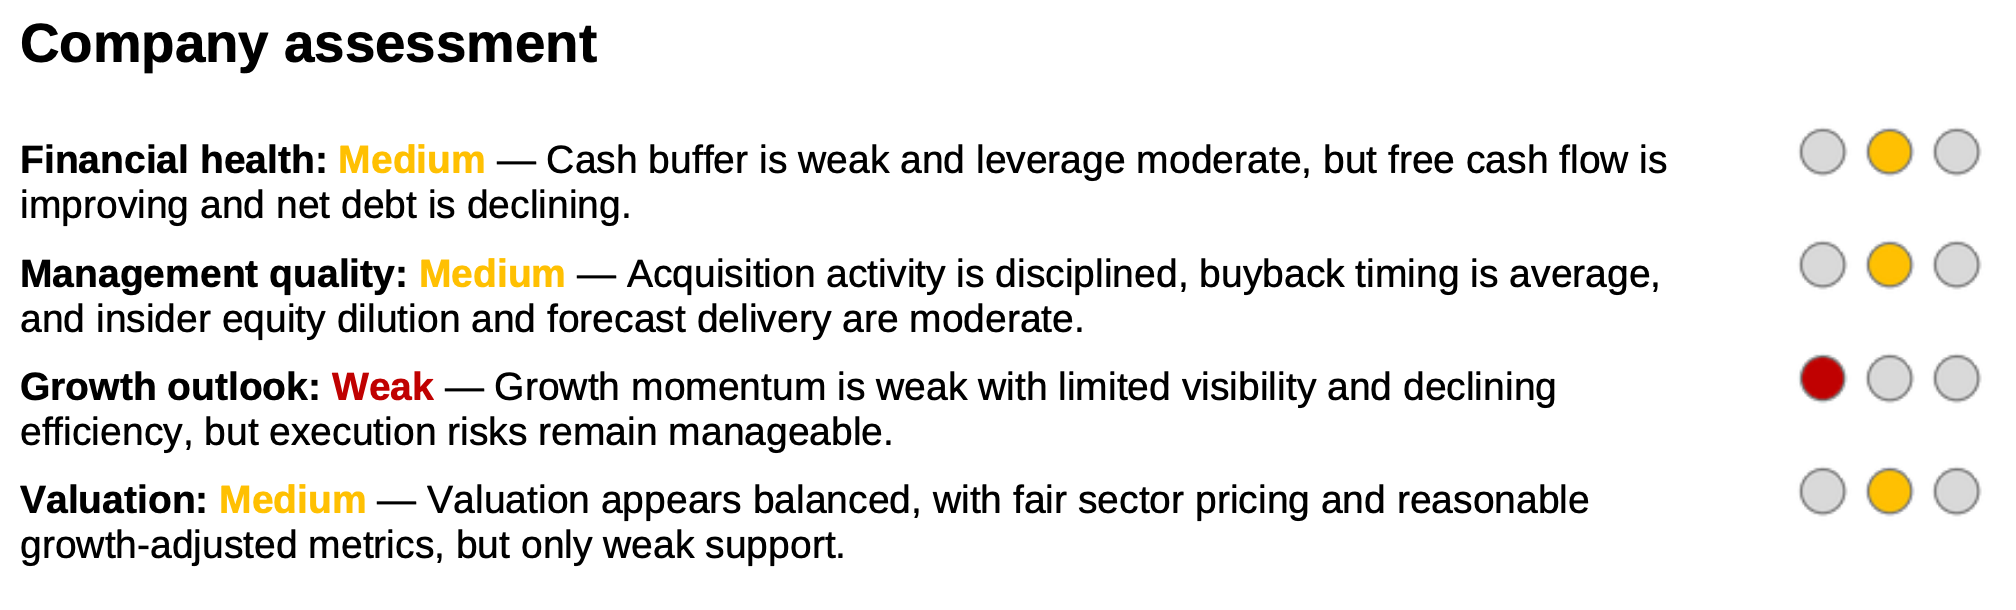
The Financial X-Ray let’s you identify strengths and pain points in seconds and shows a mixed picture for Delta:
Revenue growth: slowing
Margins: low and volatile
Free cash flow: improving but unpredictable
Net debt: improving
ROIC: weak
Valuation: attractive
There is no obvious financial red flag. This pattern reminds me of a Balance Sheet Mirage, where a strengthening balance sheet (improving debt and robust equity) mask a weakening operating engine.
The problem here is not weakness, it’s robustness.
Delta’s financial results depend heavily on variables management cannot fully control. That reduces confidence in any valuation based on a single year’s earnings or cash flow. In a nutshell, the X-Ray assigns a neutral rating to Delta, summarized below.
Why investors may misread the valuation
Let’s revisit the financial metrics table above. At roughly 11.5x earnings, Delta looks cheap. Most industrial businesses trade at 15-25x earnings.
But low multiples should be interpreted differently depending on the business behind them.
A company with recurring revenue, 30% net margin and predictable cash flows deserves a higher multiple because investors can place greater confidence in future earnings.
Delta has 10–15% EBITDA margins, significant capital requirements, volatile fuel costs and cyclical demand.
That uncertainty deserves a discount.
The historical FCF numbers make the point:
2019: $3.6bn
2020: -$7.8bn
2021: ~$0
2022: -$0.9bn
2023: $1.0bn
2024: $2.9bn
2025: $3.6bn
2026 guidance: $3-4bn
COVID explains the extreme years, but it also demonstrates how exposed airline economics are to external shocks. Right after the Pandemic, Berkshire sold all of its Airline stocks, not because of fear but because of a lack of visibility.
So the question isn’t: “Is 11.5x earnings cheap?”
It is: “Is 11.5x or 6% FCF yield cheap enough for this level of earnings uncertainty?”
Recall that investors who ask for a 10% annual return on their stock investment must also expect an annual 10% increase in FCF or earnings given the respective multiples stay at 11.5x and 6%. In 5 years, we’d have to look at a FCF of $6.8bn up from $3.5bn in 2026 (guidance) and earnings of $7.4bn up from $4.5bn.
Assuming that we’d expect a slightly higher earnings multiple of 15x and a FCF yield of 5% (optimistic airline assumptions) in 5 years, we’d still have to see 5% growth on both metrics per year.
This hasn’t been achieved over the past 7 years and judging by the variability of margins and capital spending, I do not feel comfortable making that bet.
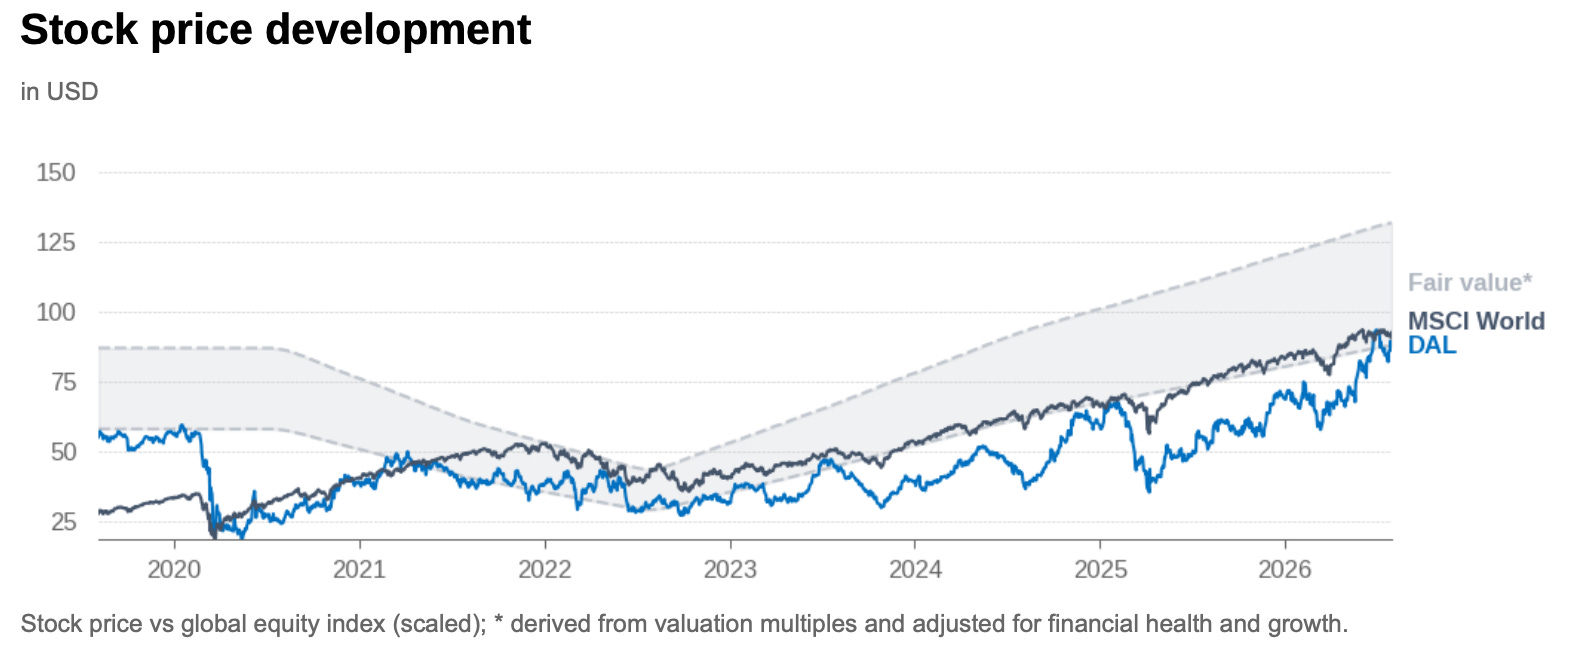
The Financial X-Ray captures that thinking for you. The stock is cheap, but it’s balance sheet support is not enough to rate it “strong” on the X-Ray score.
The insight
There are reasons to like Delta.
Debt is falling. FCF has recovered. Premium revenue is growing faster than the main cabin, and loyalty-related revenue increased 19% in Q2. Management still expects $3–4 billion of FCF in 2026 despite the current fuel headwind.
But Q2 also provides a useful reality check:
Revenue +14%. Operating profit -24%.
That is why Delta trades at a low multiple.
The stock may still be undervalued. But this looks less like a wonderful business temporarily offered at a bargain price and more like an average business available at an attractive price.
For investors, those are two very different propositions.
The Financial X-Ray makes that distinction visible: not simply whether a stock is cheap, but whether the quality and predictability of the underlying business justify taking advantage of that price.
Stocks rated “strong” on the Financial X-Ray Score have outperformed the S&P 500 since inception. I track that performance on my website. Hit the button below and give it a look.
Thanks for reading.
Thanks, Nick, for pointing me to this one. I read it properly and enjoyed it — insightful and well researched.
The first thing that came to mind: this is a textbook example of the "why would I buy the bond here and not the equity?" question I put to the analysts and the interns at my firm. Ninety percent of them stutter through the answer. And here, without even digging deeper, this looks like exactly the case where I'd rather be a debt holder than an equity holder — precisely because of that cloudy future you describe. Net debt from $27.3bn down to $16.8bn is a bondholder's story being told in an equity piece.
One point I'd push back on: Berkshire is in your headline, but the piece only covers the 2020 exit and the lack of visibility behind it. Under Abel they opened a Delta position in Q1 2026 and then raised it 44% in Q2, to 57.3m shares — around $5.4bn, 8.7% of the company. Delta is now their only airline.
Isn't that the more interesting story? Not whether 11.5x is cheap enough, but what Abel's team sees in the equity that justifies doubling down on a business whose operating income fell 24% on 13.9% revenue growth.
I made a good profit buying airline stock just after covid and holding for the recovery, but I found them so volatile and cyclical that I ended up selling my position.