

There is a simple idea behind the Financial X-Ray Selection:
Good businesses make money. Good businesses bought at attractive prices can make considerably more - and that’s the journey I’d like to share with you
The difficult part is deciding when those two conditions actually meet.
A company can have an exceptional balance sheet and still be too expensive. A stock can look cheap while its underlying business deteriorates. And a falling share price tells us almost nothing about whether the expected return has actually improved.
That’s why I built the Financial X-Ray as a systematic framework.
Every month, it evaluates more than 800 companies across financial health, management quality, growth, valuation and competitive strength. A company only enters the Selection when those factors collectively become strong enough to justify allocating capital.
That discipline has mattered.
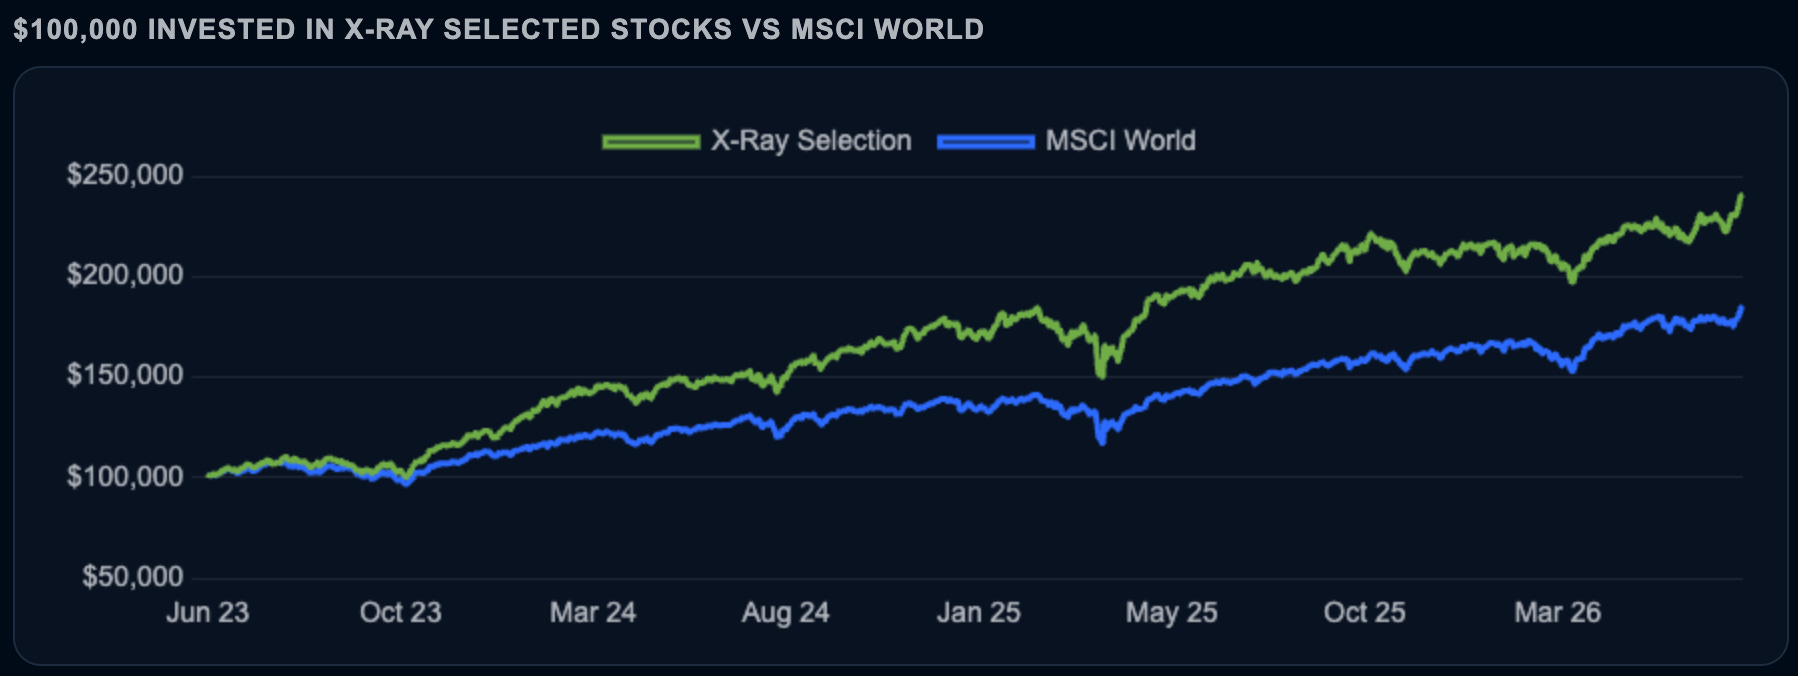
I don’t show this chart because I expect that gap to widen every year.
I show it because it illustrates what the framework is trying to achieve: attractive returns without needing to predict the next market winner.
And this month, the algorithm made two new decisions.
It added two businesses to the Financial X-Ray Selection.
One has fallen 22.8% this year.
The other is down 12.9%.
They operate in completely different industries. Their growth profiles are different. Their risks are different. Even the reasons investors have become cautious are different.
Yet the Financial X-Ray reached the same conclusion:
The price now compensates us sufficiently for those risks.
That makes them particularly interesting.
Two very different paths to the same conclusion
Before revealing the companies, let’s remove their names and look at what the framework sees.
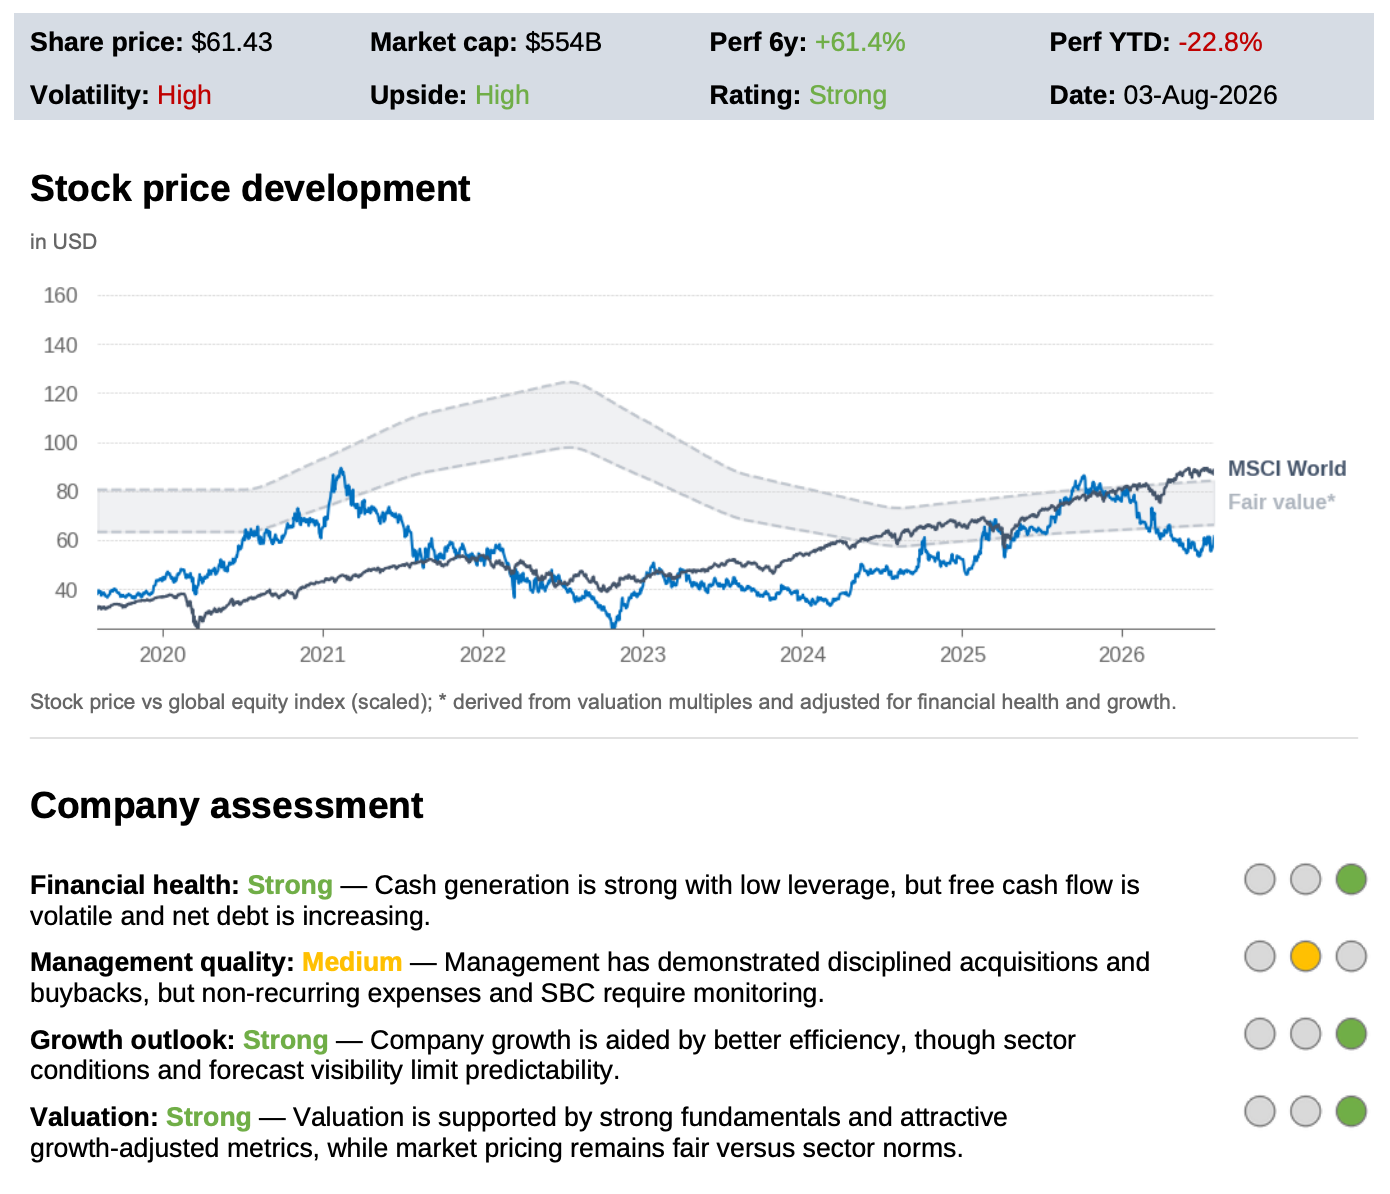
Company A offers an attractive growth profile, strong cash generation, low debt and attractive valuation backed by the balance sheet.
There is no such thing as the perfect company. Every stock has a risk profile. The Financial X-Ray is build to show you these risks and it flags important trend signals. Cash flow is volatile, debt is rising and forecast visibility is limited.
It is important to be aware of these circumstances and to evaluate them in context. The green light does just that for you.
The company’s share price is down 22.8% this year. Underneath that decline, however, the financial picture has been moving in the opposite direction.
The Financial X-Ray currently rates the business Strong overall, with Strong financial health, Strong growth and Strong valuation.
The first reason is improving profitability.
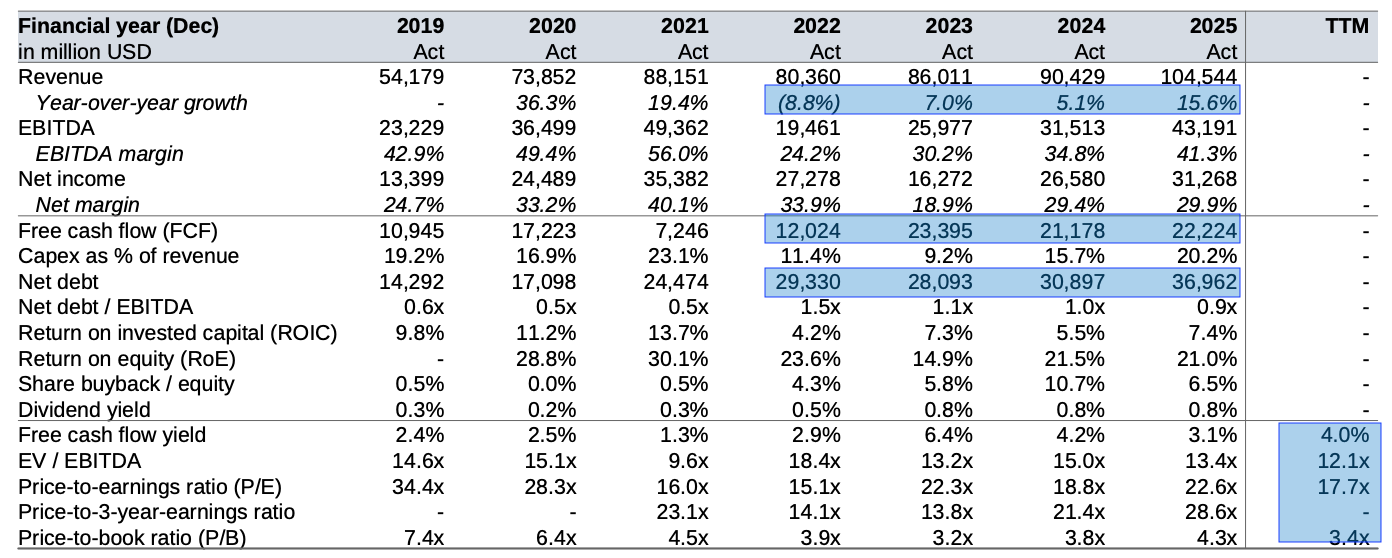
EBITDA margin fell sharply from 56% in 2021 to just 24.2% in 2022. Since then, it has recovered to 41.3% in 2025, an exceptional level of profitability.
More importantly, margins aren’t recovering while the business stagnates. Revenue growth accelerated from 5.1% to 15.6% in the latest year.
That combination matters.
When revenue growth accelerates while margins expand, earnings can grow considerably faster than sales. The company isn’t simply getting bigger; the economics of each incremental dollar of revenue are improving.
Cash generation supports that picture. Free cash flow exceeded $22 billion in 2025. It has shown some year-to-year variability, but remains substantial, while net debt of only 0.9× EBITDA leaves the balance sheet with plenty of room to manoeuvre (when net debt divided by EBITDA stays below 2x, banks usually regard a business as financially flexible).
So far, we have a growing business, margins back above 40%, strong cash generation and manageable leverage.
The stock currently trades at around 17.7× TTM earnings, while its free-cash-flow yield is approximately 4%. EV/EBITDA stands at roughly 12.1×.
For context, comparable businesses in the industry currently tend to offer free-cash-flow yields below 3% while P/E multiples frequently exceed 25×.
In simple terms, investors are currently paying a lower multiple of earnings while receiving more free cash flow for every dollar invested.
That’s why the Financial X-Ray doesn’t merely see a good business. It sees an increasingly attractive risk/reward equation.
So why is the stock down?
Because the risks are real.
Regulation remains important. Geographic and product concentration are high, and free cash flow has historically been more variable than the headline 2025 number might suggest.
You can see why the Financial X-Ray flags these issues.
But you can also see why they aren’t enough to overturn the investment case.
The balance sheet isn’t signalling financial stress. Growth isn’t deteriorating. Margins aren’t collapsing. And the valuation isn’t asking us to ignore those risks.
The risks are present, but the price increasingly compensates us for taking them.
And that brings us to the conclusion:
Strong business. Strong financial foundations. And a price that has fallen far enough for the expected return to become attractive.
The stock wasn’t selected because it fell 22.8%.
It was selected because the price fell while the underlying financial evidence remained strong and in several areas continued to improve.
That’s the distinction that makes investing interesting.
Behind the paywall you’ll see the second company and the full names.
To see what companies the FInancial X-Ray flags as attractive investments (the portfolio) and where financial health, management, growth and valuation offer an attractive risk return profile explore the platform.
