

Fast-growing software businesses are easy to like when revenue is soaring.
They become much harder to evaluate when growth slows, losses persist and shareholders are diluted through stock-based compensation. We’ve seen this across many AI and software stocks recently.
The Financial X-Ray applies a consistent framework to evaluate financial health, management quality, growth and valuation together with a simple purpose.
To buy quality stocks at decent prices.
To outperform the market without loading up on risk.
I store the results across 800+ companies on my website, ready for you to inspect.
Stocks with an X-Ray score of strong have outperformed the S&P 500 by 50% over the past 3 years.
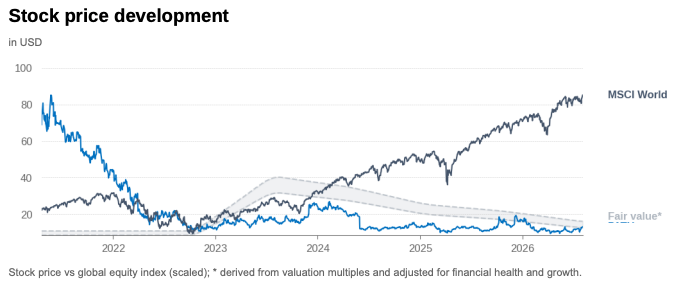
Today, one AI and automation company caught my attention. Its stock has fallen 81% over five years, yet the framework now rates the business Strong, with High upside.
Let’s look at the business underneath it and why it has finally become investable for the Financial X-Ray.
The numbers are changing
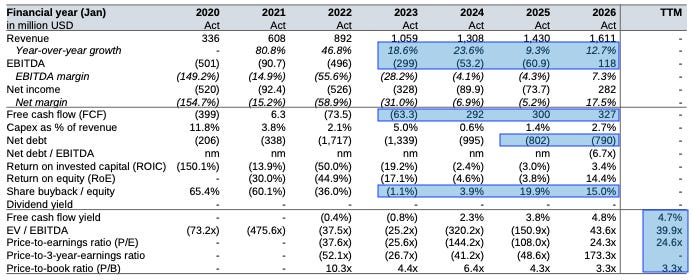
Revenue has grown from $336 million in 2020 to $1.61 billion in 2026. That’s an annual growth rate of 30%. Growth has slowed substantially from the early years, but accelerated slightly to 12.7% last year, and to 17% in the last quarter.
More important is what happened to profitability.
EBITDA improved from a $299 million loss in 2023 to a $118 million profit in 2026, taking the EBITDA margin from -28.2% to +7.3%. The recent quarterly report confirmed that trend bringing the margin above 8%.
That’s the transition I’m interested in.
Revenue is still growing, but increasingly more of that revenue is reaching the bottom line.
Let’s look at the convincing facts:
Free Cash Flow: the company generated $292 million in 2024, $300 million in 2025 and $327 million in 2026. Historically that number was driven by larges amounts of stock-based compensation (a scenario where the company pays its employees with stock options to avoid a direct cash expense). Such a situation should not persist for a long time as it weakens the position of existing equity holder and eventually employees must be paid in hard cash. But the direction is encouraging: stock-based compensation is down to 53 million from 75 million in the first quarter, while share buybacks have increased.
The business also holds substantial net cash, giving it financial flexibility while the AI market develops. A large amount of debt would be paralysing at this stage as it constraints the free allocation of capital.
So this is no longer a business promising that cash generation will eventually arrive.
It’s already here.
There is one number I’d largely ignore.
Net income jumped to $282 million in 2026, producing a 17.5% net margin. A large tax benefit contributed to that result, so I wouldn’t extrapolate the headline earnings.
Fortunately, the investment case doesn’t need it.
Positive EBITDA and three consecutive years of substantial free cash flow provide much cleaner evidence of improving underlying economics.
Stock-based compensation remains the biggest financial concern.
That’s something I’ll continue watching closely.
Why the X-Ray bought it
Put everything together:
Revenue growth is reaccelerating.
EBITDA has turned positive.
Free cash flow has exceeded $290 million for three consecutive years.
The balance sheet is strong.
Stock-based compensation is moving in the right direction.
And valuation no longer requires extraordinary future growth.
The stock currently offers a 4.7% free-cash-flow yield, while the Financial X-Ray rates its valuation Strong.
That’s why the algorithm selected it.
What could prove us wrong?
The transition is far from complete.
ROIC is only 3.4%. Profitability has a short track record. Stock-based compensation remains high. And the competitive position is only rated Medium.
Then there’s AI itself.
AI creates enormous demand for automation, but it also lowers technological barriers and increases competition.
So the question is whether this company can remain an important part of how enterprises deploy automation as AI becomes more capable.
That’s what I’d watch.
The Financial X-Ray simply tells us here:
The financial evidence has improved enough, and the valuation has fallen far enough, for the potential return to justify the remaining risks.
The stock is now part of the portfolio with a small 2% capital allocation. I see an upside potential but it comes at a certain risk worth taking.
Behind the paywall I’ll reveal the companies name and its moat.
Paid subscribers have access to the
Flagship articles highlighting stock ideas (like this one)
Entire X-Ray portfolio selection (that has outperformed the S&P 500 consistently)
Full database covering 800+ stocks (explore 100 stocks for free)
Roast my portfolio function and let the framework evaluate your portfolio
Full access to the algorithm and it’s logic
“Ask me anything, anytime” - access
All available on my website:
