

For many investors, Pfizer appears to be exactly the kind of stock value investing is built on.
It is one of the world’s largest pharmaceutical companies, owns a portfolio of globally recognized medicines and pays an attractive dividend. After the extraordinary COVID boom, the share price has fallen sharply while valuation multiples have compressed.
Many investors see opportunity. Using a different lens – the Financial X-Ray – to evaluate several financials metrics together and not in isolation, reveals an important tension beneath the surface.
Recall that low valuation only reflects an investment opportunity if the current price is based on temporary pessimism instead of fundamental deterioration.
Let’s dive into it.
What changed beneath the surface
The reason for the gradual decline of the stock over the past 4 years (post Covid) can not be found in the stock chart. We find the answer in the financial table.
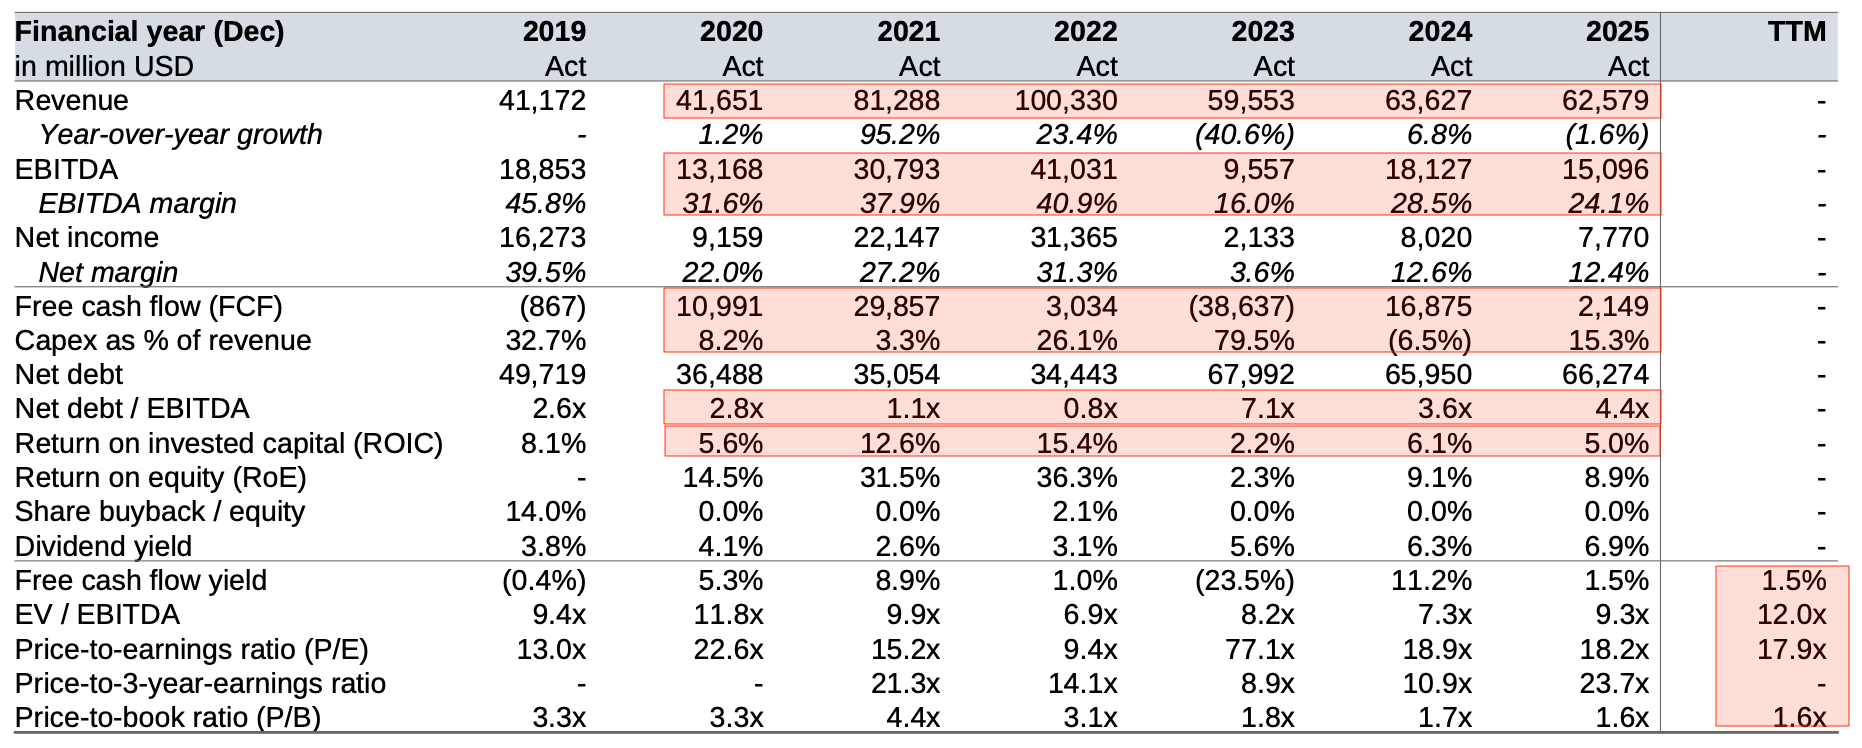
During the pandemic, Pfizer became one of the most profitable pharmaceutical companies in the world. Revenue almost doubled from $41 billion to more than $100 billion, while EBITDA margins exceeded 40%. Those numbers were extraordinary – but they were also temporary.
Once COVID-related demand faded, the business changed dramatically.
Revenue fell back to roughly $63 billion, EBITDA margins almost halved and free cash flow became one of the most volatile metrics in the entire healthcare sector.
At the same time, net debt nearly doubled following the Seagen acquisition while returns on invested capital remained well below their pandemic highs.
For context, banks usually consider a constant Net debt / EBITDA ratio below 2x as solid. Pfizer has often exceeded these level peaking at 7.1x in 2023.
When debt levels rise relative to the operating performance, financial flexibility decreases which may impact future growth, investments and distribution of capital to shareholders.
To understand why this matters, investors need context.
Revenue growth tells us whether a business continues expanding. Margins show how much profit the company earns from every dollar of sales. Free cash flow measures the cash management can actually reinvest, repay debt with or distribute to shareholders. Return on invested capital tells us how efficiently every dollar invested in the business creates future profits.
High-quality businesses usually display these metrics at a high levels, consistently over many years.
Pfizer does not.
Instead, each of the company’s key financial drivers has swung dramatically within only a few years. Take a closer look at the financials in the table again and try to anticipate the next year.
And here is the part equity analysts don’t like. Pfizer makes forecasting considerably more difficult.
The pattern at work
To determine whether a stock is genuinely cheap, analysts evaluate financial metrics together and over time.
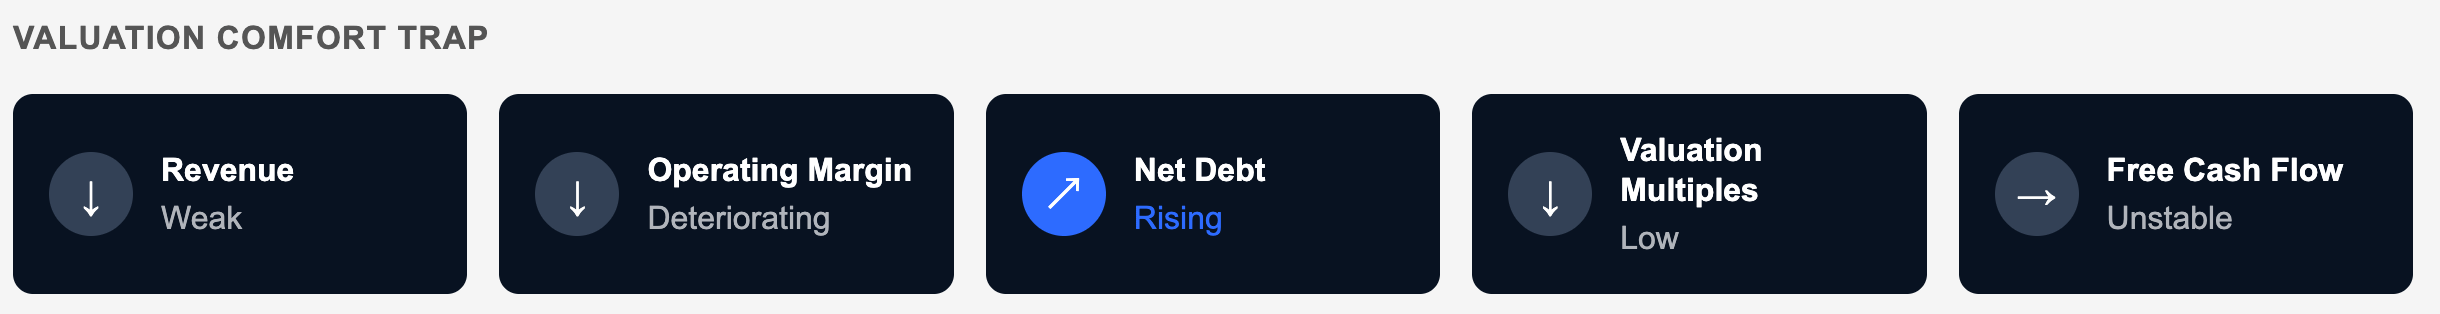
Pfizer displays a financial pattern that the Financial X-Ray framework calls a Valuation Comfort Trap. Read more here →
At first glance, the valuation looks compelling.
But valuation never exists in isolation.
When revenue, margins and free cash flow become difficult to predict, investors naturally demand a lower valuation multiple.
Low valuation does not necessarily signal hidden value.
It often reflects uncertainty about what the business will actually earn in the future.
Why investors often misread this phase and what it implies for valuation
Many investors assume valuation is determined by today’s earnings.
In reality, valuation is determined by the predictability of tomorrow’s earnings.
This is exactly what the Financial X-Ray visualizes through the fair value band.
Businesses with stable revenue, margins and cash generation tend to produce relatively stable fair value estimates.
Businesses with highly volatile fundamentals do not.
Pfizer illustrates this perfectly.
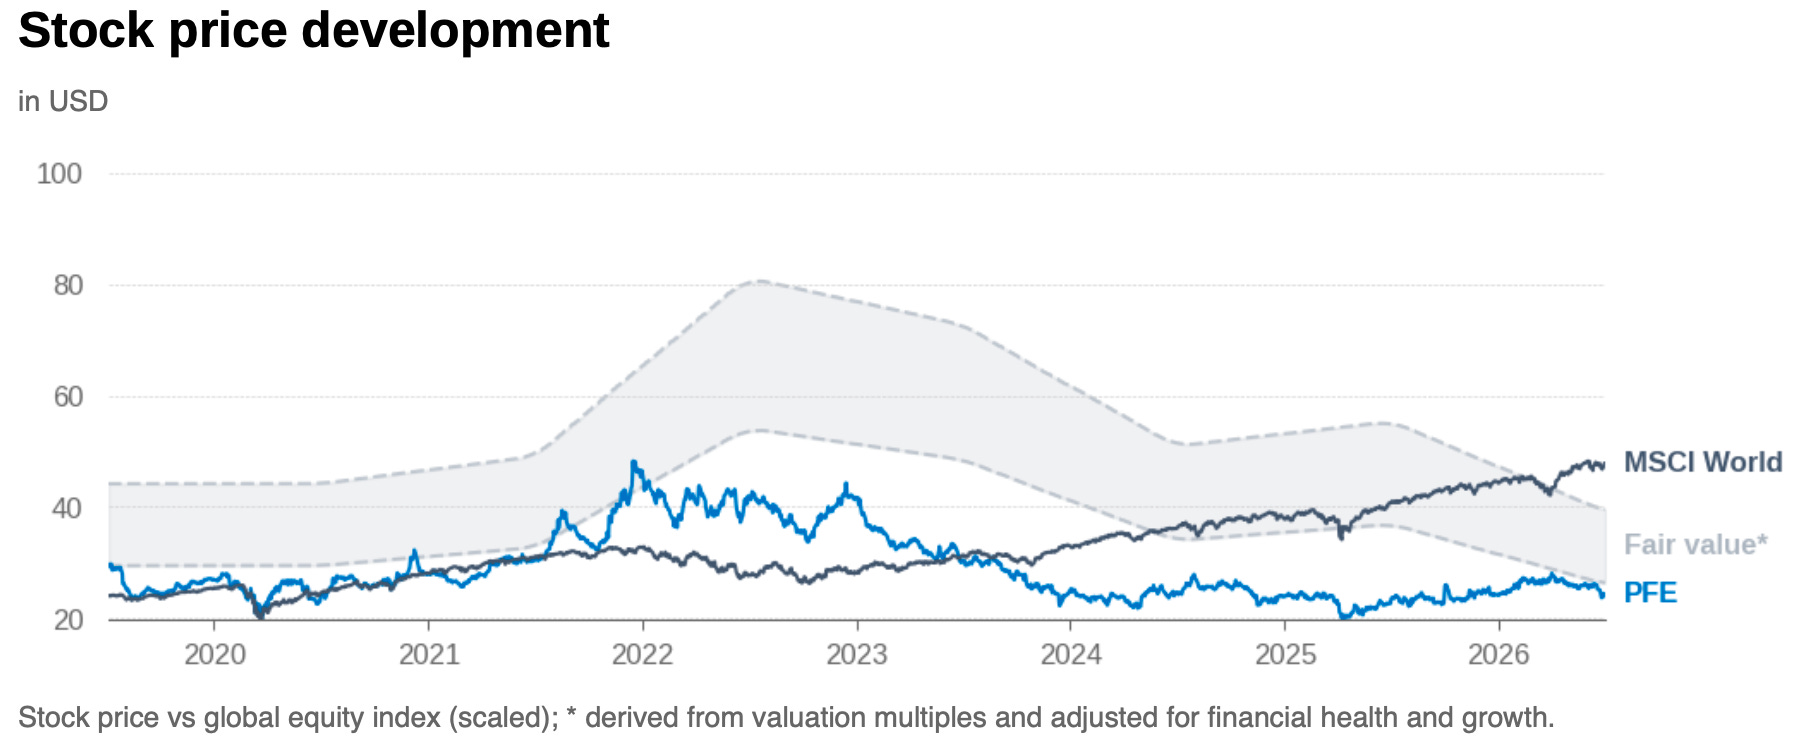
As COVID revenues surged in 2022, intrinsic value estimates rose sharply.
As those earnings disappeared, margins collapsed and free cash flow became highly volatile, the fair value band moved lower again.
The movement is not random.
It reflects changing confidence in the company’s future cash-generating ability.
Today Pfizer trades at roughly 18x earnings and slightly below the fair value band. On the surface, that appears inexpensive.
But valuation only becomes attractive if future earnings can be forecasted with confidence.
So what return do you expect from an investment in Pfizer today?
Let’s assume you want the share price to compound by 10% annually over the next decade – a rate slightly higher than the S&P 500 index – while Pfizer continues trading around 18x earnings. In that case, profits would also need to compound at roughly 10% per year.
Now let’s go back to the original problem: forecast visibility and predictability.
Does a business whose revenue has moved from $41 billion to $100 billion and back to $63 billion, whose EBITDA margins have ranged from 16% to 46%, and whose free cash flow has fluctuated from -$39 billion to +$30 billion provide that level of predictability?
That is why the stock appears inexpensive.
The market is not only pricing current earnings.
It is pricing the absolute level of earnings and uncertainty surrounding future ones.
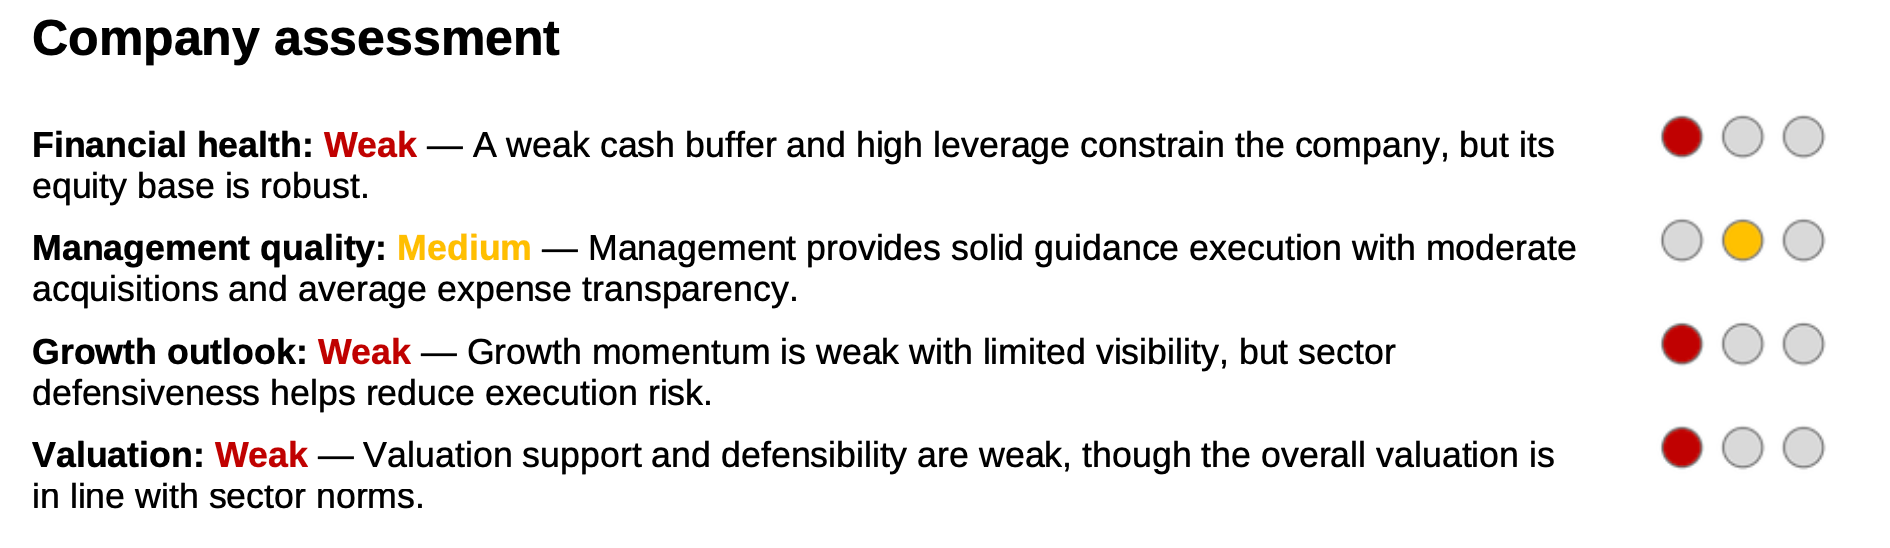
The Financial X-Ray does that kind of thinking for you and flags just that:
Financial health: weak – Volatile and falling financials
Growth outlook: weak – with limited visibility
Valuation level: weak – not supported by the balance sheet.
The insight
Investors often search for low multiples.
Professional investors search for predictable economics.
The Financial X-Ray does not conclude that Pfizer is undervalued or overvalued.
It highlights something more important:
Valuation is ultimately a function of confidence and balance sheet support.
When business quality becomes difficult to forecast, valuation naturally compresses – even if the company remains profitable.
That is why reading one ratio in isolation rarely leads to better investment decisions.
The Financial X-Ray evaluates business quality, financial health, management quality and valuation together, allowing investors to identify hidden strengths and structural weaknesses across hundreds of companies in seconds.
Because the best investment decisions begin long before looking at the valuation multiple.
Feel free to explore the Financial X-Ray platform covering 800+ stocks on my website.
Leave me a comment or share your thoughts and questions.
Thanks for reading.
Nick