

The Trade Desk helps companies buy digital ads.
Its platform lets advertisers decide where, when and at what price to buy digital advertising across connected TV, video, audio and other channels.
Unlike Google or Amazon, it does not own the advertising inventory it recommends. It primarily earns fees based on the advertising spend processed through its platform.
That model has historically produced something investors value highly: growth without requiring large amounts of capital.
Investors once paid extraordinary multiples for that combination.
Today, they don’t.
Has the price deteriorated more than the business?
In order to answer that question and to see whether the current valuation level is justified we must take a look at the financials first.
The changes I see beneath the surface
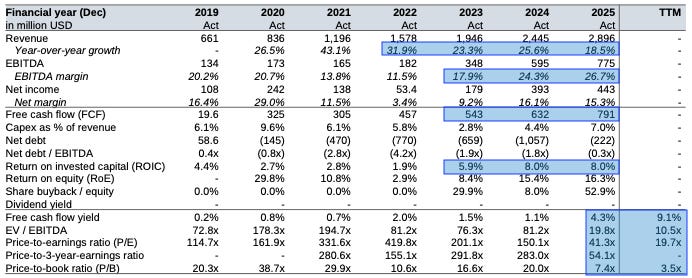
The historical financials explain why the selloff deserves attention.
Revenue increased from roughly $661 million in 2019 to $2.9 billion in 2025. That’s an annual growth of 28% over 7 years. Few companies in the technology field achieve that.
EBITDA which reflects the profitability of the operating business increased to a new high of 26% after it fell in 2021/22. During that time the company invested aggressively in people, sales, technology and the infrastructure required to support a much larger advertising platform.
Net debt has stayed negative throughout the entire time indicating full financial flexibility. This is a strong quality signal for a growing tech business.
Free cash flow rose from only $20 million to $791 million consistently. That matters because growth alone does not create value. Companies can grow by spending aggressively or by accumulating debt. The stronger signal is when additional revenue produces more cash without requiring proportionally more capital. That’s exactly what The Trade Desk did.
Return on invested capital (ROIC) shows an improvement to 8% over the past year. That figure measures the profitability on the capital spent and is a measure of efficiency. While improving, the level is not satisfactory yet and it must increase further to ~12%.
So what’s the point behind the recent selloff? Lets look at Q2 2026.
Revenue growth decelerated to 7% (first 6 months) and to 3% in Q2 only (vs 18% a year earlier)
Net margins decreased to 7.4% (first 6 months) and recovered to 9% in Q2 (vs 15% a year earlier)
That’s alarming! Even as operating cash flow increased by 20% in the first half, the increase is not entirely sustainable due to simple working capital working capital changes.
So this is not currently a story of financial deterioration. The cash machine still works. It is a story of predictability and certainty about how fast the business can grow and scale.
The pattern I see
The latest quarter changed the picture.
Revenue growth: Sharp slowdown
Operating margins: High but weakening
Free cash flow: Strong
Balance sheet: Net cash (strong)
Capital efficiency: below expectations
Valuation: Strongly compressed (cheap)
A company growing 20% can justify a much higher valuation than the same company growing 3%. At 20%, revenue roughly doubles every four years. At 3%, it takes more than two decades.
So the market is repricing the future growth embedded in the stock.
And we do not yet know whether that repricing has gone too far.
Why investors may misread this phase and valuation
For years, investors faced: Strong business + high growth + extreme valuation.
The Trade Desk repeatedly traded above 100x earnings. At those prices, investors needed years of exceptional growth simply to justify what they had already paid.
Today, the equation looks closer to:
Strong business with shaky margins + uncertain growth + compressed valuation.
That dramatically changes the return mathematics.
Say investors expect a 10% annual stock price increase over a decade and assuming The Trade Desk maintains its resilience as a business model in a stable market, it is straight forward to assume that such a business would trade at 30x earnings a decade from now. That implies a growth of only 5% per year, slightly more than the most recent quarter. But it also implies that margins do not weaken further.
That is a far easier hurdle than when investors were paying more than 100x earnings.
But this is also where the latest results matter.
Even if the investment case now considers the recent 3–7% growth as a new structural reality instead of a temporary slowdown, the numbers are achievable. Once growth returns to 10% per year investors can expect an annual stock price increase of 15% - an extraordinary return.
The stock does not need to return to its old valuation to generate attractive returns. But the business does need to recover some of its old growth and maintain profitability.
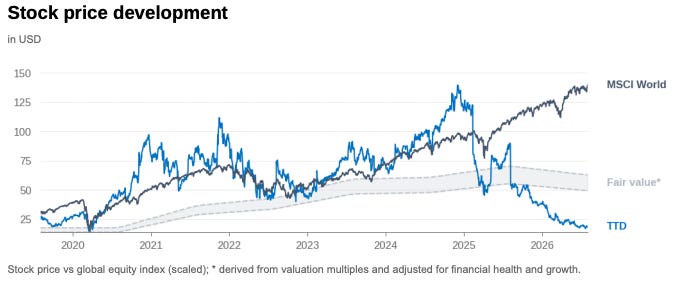
The Financial X-Ray captures the tension of declining growth and resilient fundamentals. The fair value band sits comfortably above current levels with a margin of safety but it is slightly declining to reflect the challenges of uncertainty.
The Trade Desk’s valuation has compressed sharply as growth expectations have fallen.
The insight
The Trade Desk is no longer difficult to own because of its valuation.
It is difficult to value because of its growth.
The company still generates substantial cash, carries little financial risk and has historically converted growth into increasingly attractive economics. Meanwhile, the collapse in the share price has substantially reduced the expectations investors must pay for upfront.
That creates potential upside. But it is not a free lunch.
If growth returns toward sustainable double digits, today’s valuation could offer an attractive combination of business quality and price.
If low-single-digit growth becomes normal, much of the apparent discount may simply reflect a business entering a slower phase.
The opportunity therefore isn’t that the stock has fallen.
It is the possibility that expectations have fallen further than the underlying earning power of the business.
These conclusions can be derived from a simple Financial X-Ray framework that analyses financial health, management quality, growth and valuation together and over time across 800+ stocks. Stocks selected by the framework have consistently outperformed the S&P 500.
Hi, I write on undervalued and under followed stocks. Aerospace engineer by day, research analyst/writer by night. check out my new article, https://h143capital.substack.com/p/saro-i-can-do-this-all-day?r=8sxi6s&utm_medium=ios&shareImageVariant=split